We are your trusted partner
We are fully independent which means we are loyal to our clients, not the companies we represent. When you choose to work with us, you can rest assured that we will do all of the heavy lifting.
About Our Agency
Our mission is to empower our clients with the knowledge to make the best decisions for themselves, their families, and their businesses. We always put our clients first.

We review your complete financial plan
Investment professionals want to sell you investments. Insurance professionals want to sell you insurance. We want to understand your entire financial puzzle, not just one piece.
Trusted Advice
Solid Solutions
Individual Solutions
Life insurance is the foundation upon which a solid financial future is built. We represent some of the most well-known names in the industry to find the right solutions for you.
Do you have over $7,000 in unsecured debt? Credit cards? Medical bills? Student loans? Back taxes? You may qualify to work with one of our debt resolutions specialists.
Whether you just started your first job or are planning to retire after 40 years, we have the tools that can help you accumulate wealth and protect your hard earned savings.
College funding is one thing, but college planning involves: skills assessments, college applications, grant and scholarship assistance, and a host of other complex tasks which is why we partner with the Heartland Institute.
Home and auto insurance provide financial protection against unexpected events like accidents, theft, and natural disasters, ensuring that you can recover and rebuild without facing significant financial hardship.
We offer diverse dental and vision coverage to meet your budget and health needs. With online enrollment and rates based on location instead of age, you are sure to find the perfect fit.
Medicare is complicated. With an array of Medicare options and significant rate variations, we strive to simplify the process for you, and help you select the best choice.
You insure your home and your car—but your income and earning potential are more valuable than any possession. Think of disability income insurance as protection for your paycheck.
Business Solutions
Group benefits such as health, retirement, and wellness solutions, help to foster employee satisfaction, loyalty, and productivity while reducing turnover and keeping your business competitive.
Whether you're seeking general liability, workers compensation, auto, cyber security, or any other line of coverage, we are here to help you protect your business. We can tailor your coverage to make sure you're getting exactly what your business needs.
We aim to assist businesses in managing financial records, tracking expenses, and following tax rules. With our help, businesses can simplify financial tasks and make smart choices to grow and succeed.
Offer your employees a course taught by a CFEd® certified instructor. Whether your employees need help with retirement, cash flow planning, or debt management, or other important areas of financial education, we can help.
Read Our Latest Blog Posts
The Pros and Cons of Joint Life Insurance for Couples
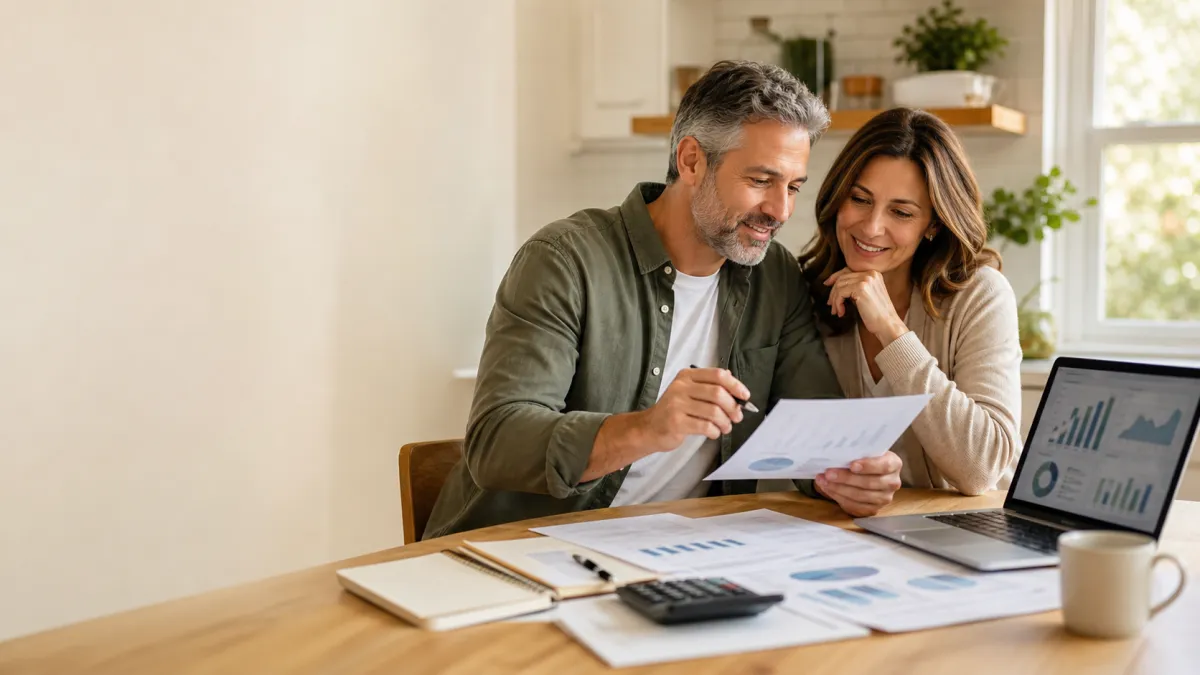
The Pros and Cons of Joint Life Insurance for Couples
When you're married or in a long-term relationship, it can seem natural to combine as many financial responsibilities as possible.
One mortgage. One household budget. One retirement plan.
So why not one life insurance policy?
Joint life insurance is designed to cover two people under a single policy. It can be an attractive option for some couples, but it isn't automatically the best choice for everyone.
Before deciding whether joint coverage makes sense, it's important to understand how these policies work, what they can accomplish, and where they may fall short.
What Is Joint Life Insurance?
Joint life insurance covers two people under one policy rather than having each person purchase an individual policy.
There are two primary types of joint life insurance:
First-to-Die Life Insurance
A first-to-die policy pays a death benefit when the first person dies.
For example, if a married couple owns a first-to-die policy and one spouse passes away, the surviving spouse receives the death benefit.
The policy generally ends after the benefit is paid.
This type of coverage is primarily designed to provide financial protection for the surviving spouse or other beneficiaries after the first death.
Second-to-Die or Survivorship Life Insurance
A second-to-die policy works differently.
Instead of paying when the first person dies, it pays after both insured individuals have died.
These policies are often used for estate planning and wealth transfer rather than replacing income for a surviving spouse.
For example, a couple may use a survivorship policy to provide funds for children, grandchildren, or other beneficiaries after both spouses have passed away.
That distinction is extremely important because these two types of policies serve very different purposes.
Potential Benefits of Joint Life Insurance
1. It Can Simplify Financial Planning
Managing one policy instead of two can be appealing to couples who prefer to keep their finances simple.
Instead of maintaining separate policies, premiums, and paperwork, everything can be handled under one policy.
For some couples, that simplicity is valuable.
2. It Can Be Useful for Estate Planning
Survivorship life insurance can be particularly useful as part of an estate planning strategy.
Because the death benefit is paid after both insured individuals have passed away, the policy can provide liquidity for beneficiaries and may be used as part of a broader estate or wealth-transfer plan.
This can be especially relevant for families with substantial assets or specific inheritance goals.
Estate planning strategies can have significant tax and legal implications, so couples considering this approach should work with qualified estate planning and tax professionals.
3. It May Help When One Person Is Difficult to Insure
Here's an interesting advantage that many people don't realize.
In certain situations, a survivorship policy may make coverage possible when one spouse has significant health issues that could make an individual policy difficult or expensive to obtain.
Because the policy is based on the combined risk of both insured individuals, the underwriting may work differently than it would for an individual policy.
That doesn't mean every couple will qualify, but it's one reason joint coverage can sometimes be worth exploring.
4. It Can Help Accomplish a Specific Legacy Goal
For couples who primarily want to leave money to their children, grandchildren, or a charity after both spouses have passed away, survivorship insurance can be an effective tool.
Rather than focusing on replacing income for the surviving spouse, the policy is designed around what happens after the second death.
Potential Drawbacks of Joint Life Insurance
Joint coverage isn't right for every couple.
In fact, there are several situations where two individual policies may make more sense.
1. The Coverage Isn't Always Equal to Your Individual Needs
Imagine a husband earns $150,000 per year while his wife earns $50,000.
Their individual financial responsibilities may be very different.
A single joint policy may not provide the flexibility needed to adequately protect each person's income and obligations.
With individual policies, each spouse can have a different coverage amount based on their own financial responsibilities.
2. Divorce or Separation Can Complicate Things
Nobody enters a marriage expecting it to end.
But life doesn't always go according to plan.
If a couple separates or divorces, figuring out what happens to a joint life insurance policy can become complicated.
Depending on the policy, ownership structure, and circumstances, separating the coverage may not be as simple as dividing other financial accounts.
That's one reason couples should think carefully about the long-term flexibility of their coverage.
3. A First-to-Die Policy Ends After the First Death
With a first-to-die policy, the death benefit is paid when the first insured person dies.
Once that happens, the policy generally ends.
That means the surviving spouse may still need life insurance—but may now have to purchase a new policy at an older age and potentially with different health circumstances.
That's an important consideration that couples sometimes overlook.
4. Your Health Could Change
This is another reason individual policies can be attractive.
Suppose a couple purchases one joint policy and several years later one spouse develops a serious medical condition.
If the couple later decides they want separate coverage, the spouse with the health condition may have difficulty qualifying for an affordable individual policy.
Having individual coverage from the beginning can provide greater independence and flexibility.
So, Should Couples Buy Joint or Individual Life Insurance?
There's not a one size fits all answer.
For many couples, two individual policies provide the greatest flexibility because each person can have coverage tailored to their income, health, debts, and financial responsibilities.
But that doesn't mean joint life insurance is a bad option.
It can make a lot of sense when the couple has a specific goal, particularly estate planning or wealth transfer.
The key is understanding what you're trying to accomplish before choosing the policy.
Ask yourself:
Are we primarily protecting each other's income?
Do we want coverage after the first death or after both of us have died?
Do we have children or other dependents?
Do we have significant assets that require estate planning?
Does one spouse have health issues that affect insurability?
How important is flexibility if our circumstances change?
Those questions can help determine which strategy deserves a closer look.
The Bottom Line
Joint life insurance can offer simplicity and may be an effective strategy for certain couples, particularly when estate planning or wealth transfer is the primary goal.
But it isn't automatically cheaper or better than having two individual policies.
For many families, individual policies provide more flexibility and allow each spouse's coverage to be designed around their unique financial situation.
The right answer depends on what you're trying to protect and what you want the policy to accomplish.
And that's exactly why it's worth looking at your options before simply choosing the policy that appears easiest.
Ready to Compare Your Options?
If you're married or in a long-term relationship and aren't sure whether joint or individual life insurance makes more sense, we're happy to help you compare the options.
We'll look at your individual circumstances, explain how the different strategies work, and help you determine what makes the most sense for your family.
No pressure. Just a straightforward conversation about protecting your financial future.
Let's work together!
Start with a complimentary financial needs analysis. This will give you a chance to meet us and to see how we can help you achieve your dream.
Our Trusted Partners
Life - Annuity - Health
Home - Auto - Business
Our Trusted Partners
Life - Annuity - Health
Home - Auto - Business
Office:
450 St. John Rd. #2039
Michigan City, IN 46361
Call or Text:
219-259-5835
Email: [email protected]
Site:
www.bairandassociates.com