We are your trusted partner
We are fully independent which means we are loyal to our clients, not the companies we represent. When you choose to work with us, you can rest assured that we will do all of the heavy lifting.
About Our Agency
Our mission is to empower our clients with the knowledge to make the best decisions for themselves, their families, and their businesses. We always put our clients first.

We review your complete financial plan
Investment professionals want to sell you investments. Insurance professionals want to sell you insurance. We want to understand your entire financial puzzle, not just one piece.
Trusted Advice
Solid Solutions
Individual Solutions
Life insurance is the foundation upon which a solid financial future is built. We represent some of the most well-known names in the industry to find the right solutions for you.
Do you have over $7,000 in unsecured debt? Credit cards? Medical bills? Student loans? Back taxes? You may qualify to work with one of our debt resolutions specialists.
Whether you just started your first job or are planning to retire after 40 years, we have the tools that can help you accumulate wealth and protect your hard earned savings.
College funding is one thing, but college planning involves: skills assessments, college applications, grant and scholarship assistance, and a host of other complex tasks which is why we partner with the Heartland Institute.
Home and auto insurance provide financial protection against unexpected events like accidents, theft, and natural disasters, ensuring that you can recover and rebuild without facing significant financial hardship.
We offer diverse dental and vision coverage to meet your budget and health needs. With online enrollment and rates based on location instead of age, you are sure to find the perfect fit.
Medicare is complicated. With an array of Medicare options and significant rate variations, we strive to simplify the process for you, and help you select the best choice.
You insure your home and your car—but your income and earning potential are more valuable than any possession. Think of disability income insurance as protection for your paycheck.
Business Solutions
Group benefits such as health, retirement, and wellness solutions, help to foster employee satisfaction, loyalty, and productivity while reducing turnover and keeping your business competitive.
Whether you're seeking general liability, workers compensation, auto, cyber security, or any other line of coverage, we are here to help you protect your business. We can tailor your coverage to make sure you're getting exactly what your business needs.
We aim to assist businesses in managing financial records, tracking expenses, and following tax rules. With our help, businesses can simplify financial tasks and make smart choices to grow and succeed.
Offer your employees a course taught by a CFEd® certified instructor. Whether your employees need help with retirement, cash flow planning, or debt management, or other important areas of financial education, we can help.
Read Our Latest Blog Posts
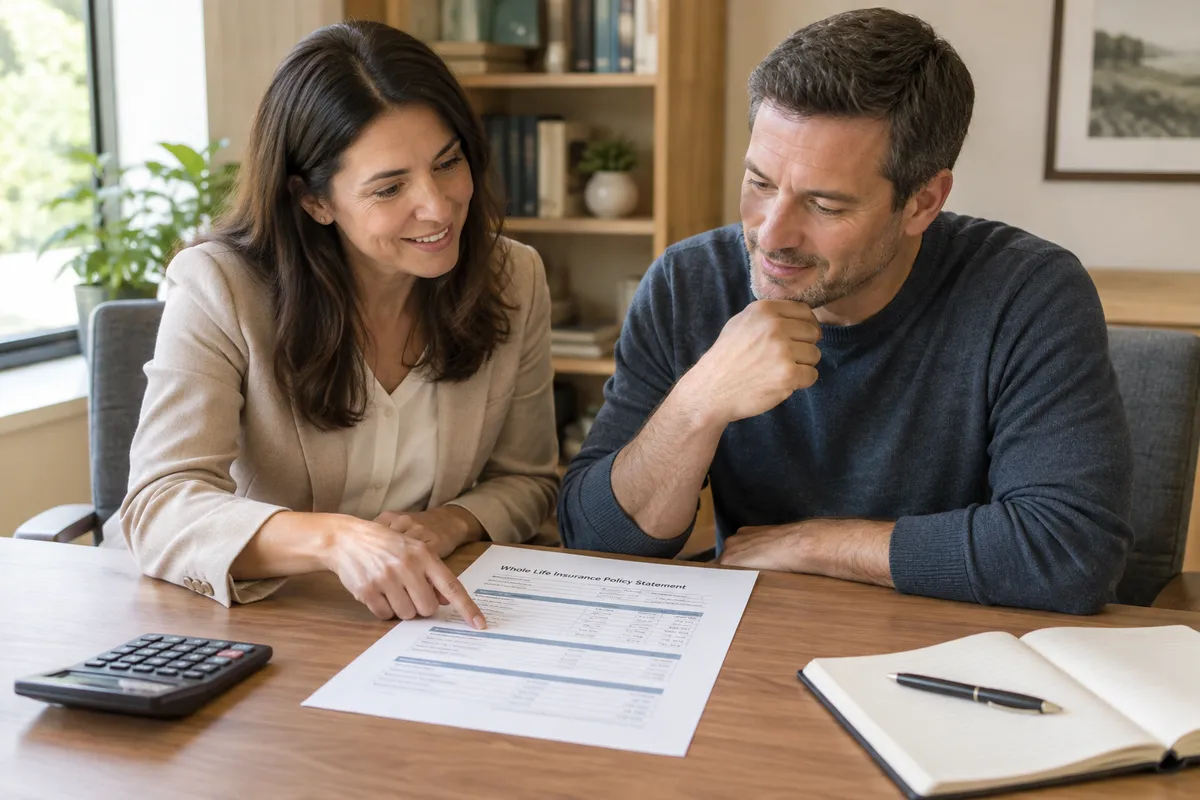
Life Insurance and Dividends: Making the Most of Your Policy
Life Insurance and Dividends: Making the Most of Your Policy
When people hear the word dividends, they often think of stocks, investments, and quarterly payments. But did you know that some life insurance policies can pay dividends, too?
If you own an eligible participating whole life insurance policy, you may have several options for using those dividends. Depending on your goals, you could receive the money directly, use it to reduce your premium, or purchase additional life insurance.
The important thing is understanding what your options mean and how they fit into your overall financial plan.
Let's take a closer look at how life insurance dividends work and what you should consider before deciding what to do with yours.
What Are Life Insurance Dividends?
Life insurance dividends are payments that may be made to owners of certain participating whole life insurance policies.
These dividends generally reflect the insurance company's financial experience, including investment performance, claims, and operating expenses. When the company's experience is more favorable than anticipated, it may have a surplus available to distribute to eligible policyholders.
However, life insurance dividends are not guaranteed. An insurance company's history of paying dividends doesn't guarantee that it will continue paying them at the same level in the future.
It's also important to understand that life insurance dividends aren't the same as stock dividends. They don't represent ownership in a publicly traded company, and the dividend amount isn't a guaranteed investment return.
Not every life insurance policy pays dividends. Term life insurance policies generally don't offer them, and some permanent life insurance policies are nonparticipating and aren't eligible for dividends.
If you have a participating whole life policy, review your policy documents or contact your insurance professional to understand which options are available to you.
Four Ways to Use Life Insurance Dividends
If your policy pays dividends, you may have several choices. The options available depend on your particular policy and insurer, but four common choices are cash payments, premium reductions, paid-up additions, and leaving dividends to accumulate with interest.
1. Receive Your Dividends in Cash
Sometimes, the simplest option is the right one.
Depending on your policy, you may be able to receive your dividends directly rather than applying them to the policy.
You could use the money for everyday expenses, build up your emergency savings, pay down debt, or put it toward another financial goal.
For example, imagine your policy pays a $600 dividend for the year. You might decide that having the extra $600 available for an upcoming expense is more useful than increasing your life insurance coverage.
This option gives you flexibility, but remember that dividends aren't guaranteed to remain at the same level from year to year.
Also, the tax treatment depends on how the dividend is handled and your policy's circumstances. If the insurer pays interest on dividends you leave with the company, that interest is generally taxable income.
2. Use Dividends to Reduce Your Premiums
Another option is applying dividends toward your policy premiums.
This can reduce the amount you need to pay out of pocket to maintain your coverage.
For example, suppose your annual premium is $1,800 and your policy provides a $500 dividend. If the dividend is applied to your premium, you would generally need to cover the remaining $1,300 yourself.
That can make an existing policy more manageable without requiring you to change your coverage simply because your budget has changed.
However, there's an important distinction: a dividend used to reduce premiums isn't a guarantee that your policy will remain affordable indefinitely. Because dividends can change, you should understand how much of your premium is contractually guaranteed and how much depends on future dividends.
If you rely on dividends to cover part of your premium, ask your insurance professional what would happen if future dividends were lower than expected.
3. Purchase Paid-Up Additional Insurance
For some policyholders, using dividends to purchase paid-up additions can be an attractive long-term strategy.
Paid-up additions are small amounts of additional whole life insurance purchased with the dividend. They generally don't require ongoing premiums of their own, and they can increase the policy's death benefit and cash value.
Depending on the policy, paid-up additions may also be eligible to receive future dividends.
Imagine that you already have a whole life policy intended to provide long-term protection for your family. Rather than taking each year's dividend in cash, you choose to purchase additional paid-up coverage.
Over time, those additions can increase the total amount of insurance your beneficiaries may receive and the policy's available cash value.
This option may appeal to people who want to increase their coverage or build additional value within an existing policy.
However, the results depend on the policy's terms, the dividends actually paid, and other factors. Paid-up additions should not be viewed as guaranteed investment growth.
Before choosing this option, ask for an illustration showing how the policy is expected to perform and which values are guaranteed versus non-guaranteed.
4. Leave Dividends With the Insurance Company to Accumulate
Some policies allow dividends to remain with the insurer and earn interest.
This may appeal to policyholders who don't need the money immediately and prefer to keep it available for future use.
However, this option deserves careful consideration. Interest credited to dividends left with the insurance company is generally taxable, even when the original policy dividends would otherwise be treated as a return of premium.
You should also compare the insurer's interest rate and withdrawal terms with other places you could keep your savings.
Leaving dividends with the insurer isn't automatically the best choice simply because the money remains associated with your life insurance policy.
Which Dividend Option Is Right for You?
There isn't one dividend option that's best for everyone.
The right choice depends on what you want your life insurance policy to accomplish and what your broader financial situation looks like.
Here are a few questions worth asking yourself:
Do you need the money today? Receiving dividends in cash may provide flexibility for current expenses or other priorities.
Are your premiums becoming difficult to manage? Applying dividends toward premiums may reduce your out-of-pocket costs, although future dividends aren't guaranteed.
Do you want additional life insurance? Paid-up additions may increase your death benefit and cash value.
Are you saving for a future goal? Leaving dividends to accumulate may be an option, but compare the interest rate, tax treatment, and available alternatives.
Has your financial situation changed? A strategy that made sense when you purchased your policy may not be the best fit today.
Your answers can help you determine which option deserves a closer look.
Don't Choose Based on Dividends Alone
It's easy to focus on the dividend when reviewing a participating whole life policy. After all, receiving additional value from an existing policy can be appealing.
But dividends are only one part of the picture.
You should also understand your policy's premiums, death benefit, cash value, guarantees, and long-term costs. If you're comparing policies, look at the overall contract and its projected performance rather than judging it solely by the insurer's current dividend scale.
And if your financial goals have changed, don't assume you need to keep doing the same thing with your dividends year after year.
A conversation with a qualified insurance professional can help you understand the available choices and the tradeoffs involved.
If you're considering surrendering a policy, making withdrawals, or taking a loan against its cash value, get advice before acting. Depending on the circumstances, those decisions can affect your coverage, available cash value, and tax situation.
What About Taxes on Life Insurance Dividends?
Tax treatment is another important consideration.
Life insurance policy dividends are generally treated as a return of premium up to the amount of your investment in the contract. However, interest earned on dividends left with the insurer is generally taxable.
Other transactions involving a policy such as surrendering it, taking certain distributions, or allowing a policy to lapse with an outstanding loan can have different tax consequences.
Because the details matter, it's wise to consult a qualified tax professional if you're unsure how a particular transaction will affect you.
The goal is to understand the full financial impact before making a change.
Make Your Policy Work for Your Goals
Life insurance dividends can give eligible policyholders additional flexibility. You may be able to receive them as cash, use them to reduce premiums, purchase paid-up additions, or leave them to accumulate with interest.
But the best choice isn't necessarily the one that produces the largest projected policy value or the biggest immediate payment.
It's the one that makes sense for your needs, your budget, and the purpose of your coverage.
If you own a participating whole life policy and aren't sure how to handle your dividends, consider reviewing your policy and the options available to you.
At Bair & Associates, we believe financial decisions should begin with education. If you have questions about your life insurance policy or want to better understand your options, we're happy to help you explore them without pressure.
Sometimes, making the most of what you already have starts with simply understanding it better.
Let's work together!
Start with a complimentary financial needs analysis. This will give you a chance to meet us and to see how we can help you achieve your dream.
Our Trusted Partners
Life - Annuity - Health
Home - Auto - Business
Our Trusted Partners
Life - Annuity - Health
Home - Auto - Business
Office:
450 St. John Rd. #2039
Michigan City, IN 46361
Call or Text:
219-259-5835
Email: [email protected]
Site:
www.bairandassociates.com